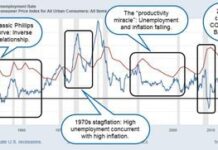
Monetarism is a school of economic thought that places the total amount of money at the center of the economy. We believe that the money supply is the main driver of short-term economic activity. The American economist Milton Friedman is widely recognized as the leader of this approach. His work, along with other monetarists, challenged the previously dominant Keynesian model. This view received considerable attention in the 1970s and early 1980s, when inflation was on the rise and traditional policies seemed to be failing.
How the equation of exchange works
The core of monetarist theory is based on a certain formula called the equation of exchange. It is written as MV = PQ. Understanding this equation is important to understanding how monetarists believe the economy works.
- M represents the money supply. This includes coins, currency and bank deposits.
- V represents the velocity of money. This is how many times an average dollar of the money supply is spent on goods and services per year.
- P is the average price level of goods and services.
- Q represents the quantity of goods and services produced.
Monetarists believe that cause and effect run from left to right in this equation. If V (velocity) is constant and predictable, an increase in M (money supply) will lead to an increase in P (price) or Q (output). If Q increases with M, P remains relatively stable. However, if the rise in Q does not match the rise in money, P will rise. Simply put, changes in the money supply directly determine the levels of output, employment and prices. The problem is that these effects don’t happen overnight. They only become apparent after a considerable delay.
The Monetary Rule vs. Fiscal Policy
The main conclusion of this theory is the rejection of discretionary fiscal policy. Monetarists, on the other hand, advocate “monetary rule”. This idea has been deeply influenced by the book “Monetary History of the United States, 1867-1960”. Published in 1963, the book was written by Friedman and Anna J. Schwartz. They conducted a comprehensive analysis of the US money supply from the end of the Civil War to 1960. This detailed historical data helped other economists take monetarism seriously.
Friedman believed that the government should promote economic stability. However, he argued that this could only be achieved by controlling the growth rate of the money supply. The proposed method is a simple fixed rule. The government should increase the money supply by a certain percentage every year. This ratio is tied to the potential growth rate of gross domestic product (GDP). For example, if the economy is allowed to grow by 3%, the money supply can be allowed to grow by 3% to 5%.
The goal is to ensure stable economic growth and low inflation. Monetarists believe that by keeping money growth moderate and predictable, they can stabilize prices and support production without the fluctuations caused by repeated government intervention.
Why this theory struggled in the 1980s
Before the changes in the US economy in the 1980s, the link between money supply growth and economic growth seemed strong. Many factors proved the monetarist predictions wrong.
First, the financial world has changed. A new hybrid type of bank deposit has appeared. These instruments overshadow the traditional savings categories that economists use to calculate the money supply. It’s getting harder and harder to define exactly what M is.
Second, inflation has slowed down. Low inflation changes consumer behavior. People hold onto cash longer because it doesn’t lose value as quickly. This reduces the velocity of money (V ). When V is no longer constant, the equation MV = PQ becomes less reliable in its predictions.
These structural changes weaken the decision-makers’ ability to predict the effect of money supply growth on nominal GDP. Monetary stability rules were once considered a solution to inflation, but as economies developed, they lost their predictive power.
“Monetarists believe that stable and moderate growth in the amount of money can often ensure stable economic growth and low inflation.”
The failure of this model in the 1980s highlighted its fundamental limitations. Economic mechanisms are not static. As economic innovations and consumption habits change, rigid rules based on historical data may become irrelevant. While the debate over how best to manage the money supply continues, the era of strict monetarist controls is largely over.